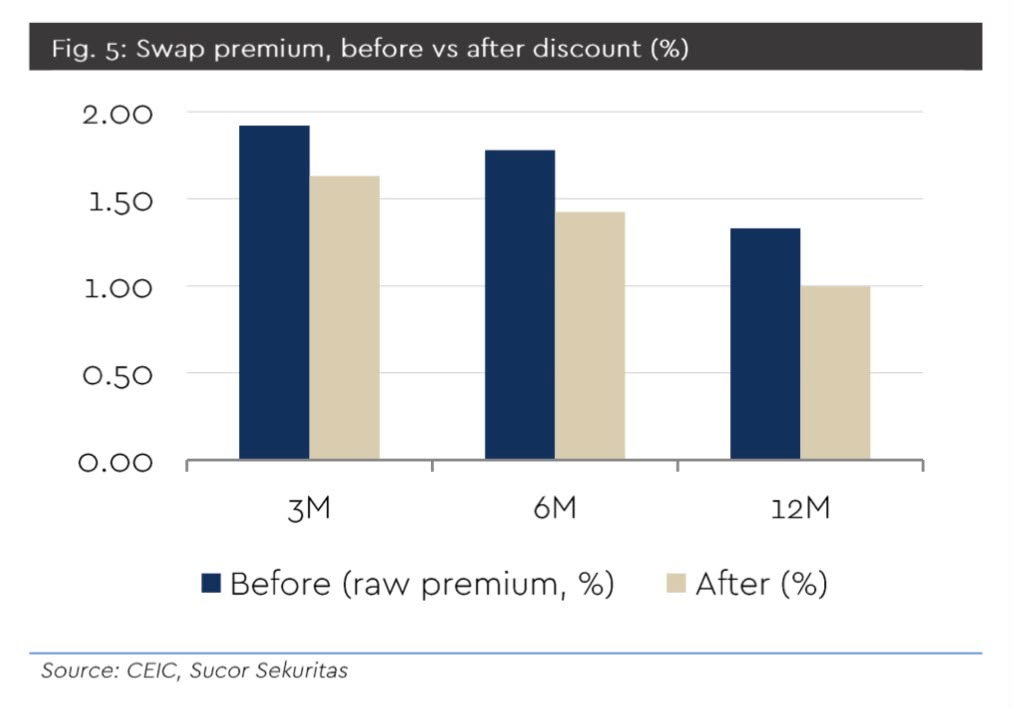
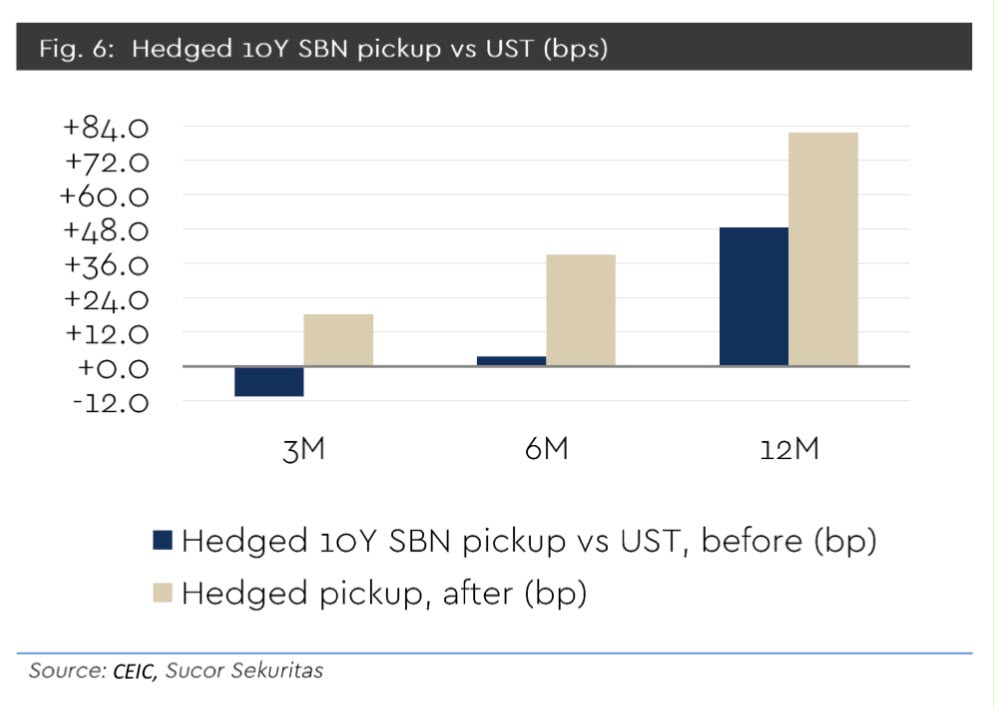
BI has shifted from absorbing rupiah liquidity toward supporting it. While BI-Rate remains at 5.75%, the key change is in its policy toolkit, with cheaper hedging and stronger incentives for longer tenors. The swap premium discount has moved from a flat 12.5% to a tiered structure, while DNDF discounts have also been increased. As hedging costs become cheaper, the attractiveness of hedged SBN improves, with the hedged 10Y SBN pickup over UST reaching +82bps.
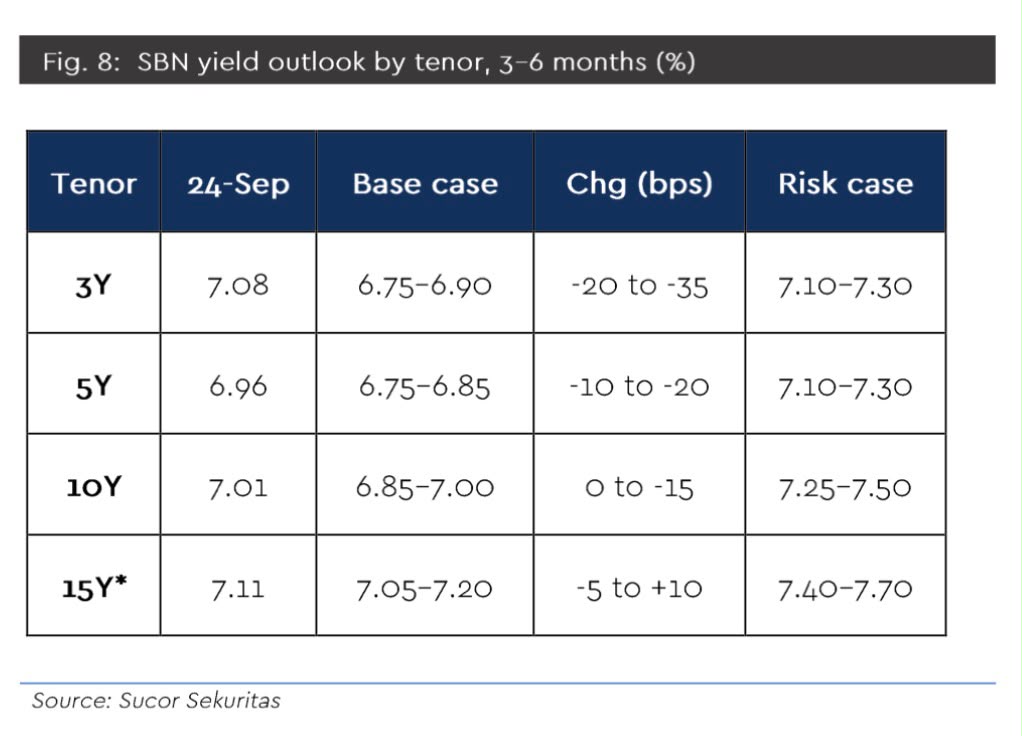
The larger shift is structural. PMK 67/2026 removes BI as a placement option for surplus government cash, which must now be directed toward banks or SBN. With Rp299tn already placed at state banks, previously idle government cash is increasingly being converted into system liquidity. This supports our economists’ bull-steepening view over the next 3–6 months, with the 3Y expected to lead the move as yields decline, followed by the 5Y and 10Y, while the 15Y remains relatively anchored.
The key catch is the rupiah. At around 17,900 and with only a 182bps SBN–UST spread, additional rupiah liquidity could instead chase USD, limiting the positive impact on SBN. Our economists therefore see a 25bps BI hike in 4Q26 as a possibility if FX pressure intensifies. The bull-steepening view would turn into a bear-steepening scenario if USDIDR breaks 18,500 or 10Y UST rises above 5.5%.