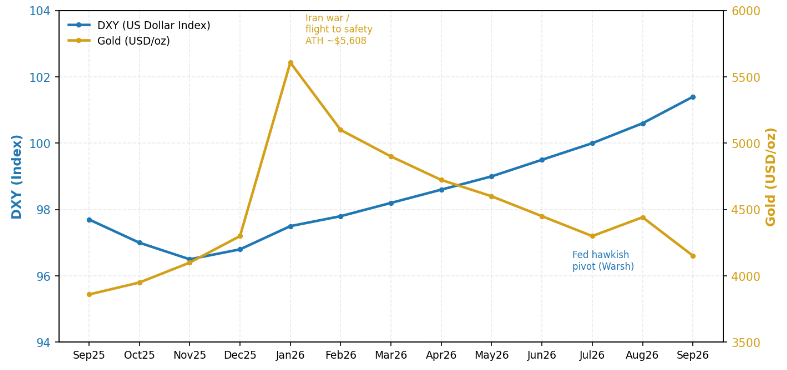
Macro risks are intensifying — 10Y Treasury yields have surged above 5.2%, their highest since 2007, alongside rising oil prices and stretched AI valuations. We see two distinct Fed paths ahead: further tightening (Volcker-style) or a pivot toward yield curve control (YCC). Rather than predict which one plays out, the priority is preparing for both, since each favors very different assets — higher yields and a stronger USD in the first scenario, versus gold and liquidity-driven equity support in the second.
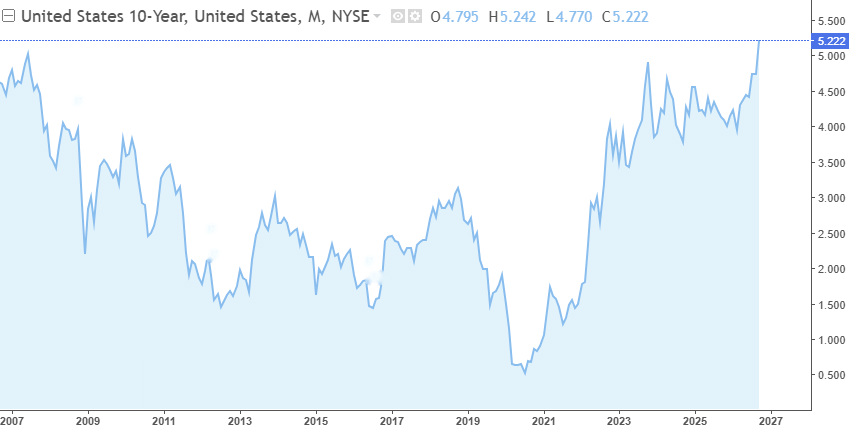
For Indonesia, the "higher-for-longer" scenario is the bigger near-term concern. Heavy Treasury supply, trade uncertainty, resilient US growth, and elevated oil prices are all pressuring bond demand — and if payrolls and inflation stay firm, the Fed may be forced to tighten further. That risk could spill into domestic yields and add pressure to an Indonesian equity market already down roughly 30% YTD. In this scenario, we'd favor overweighting cash and short-duration instruments, and companies with US dollar earnings or meaningful export exposure, which are better positioned to benefit from a stronger dollar.
The alternative path — a Fed pivot toward 1940s-style yield curve control — would cap Treasury yields and likely push real yields lower, which is constructive for gold given elevated inflation. Continued Fed bond purchases in that scenario could also expand liquidity and support equities broadly. For Indonesia specifically, lower US yields and a softer dollar would ease capital outflow pressure and support domestic rates — though actual equity performance would still hinge on fiscal discipline and investment-friendly government policy.
Given the uncertainty, we favor a barbell strategy — at least 25% cash paired with selective Indonesian equities and short-duration instruments. Preferred names: ISAT (37% stake in ZanKore, neocloud exposure), AMMN (copper/gold exposure), and MBMA (depressed nickel prices, stock-specific upside). ADMR and AADI remain our preferred commodity exposures. Elevated cash provides downside protection, attractive carry, and dry powder to capitalize on dislocations as they emerge.