BI Rate decision due today (Sept 22-23) — this remains the key catalyst for IHSG, with consensus leaning toward a hold, though a Fed-driven hike is still possible given Indonesia's USD dependency and the resulting rate differential. Much of this is already priced in via SRBI auction data, so today's market reaction likely hinges on whether the outcome matches consensus or surprises to the upside, rather than the decision itself.
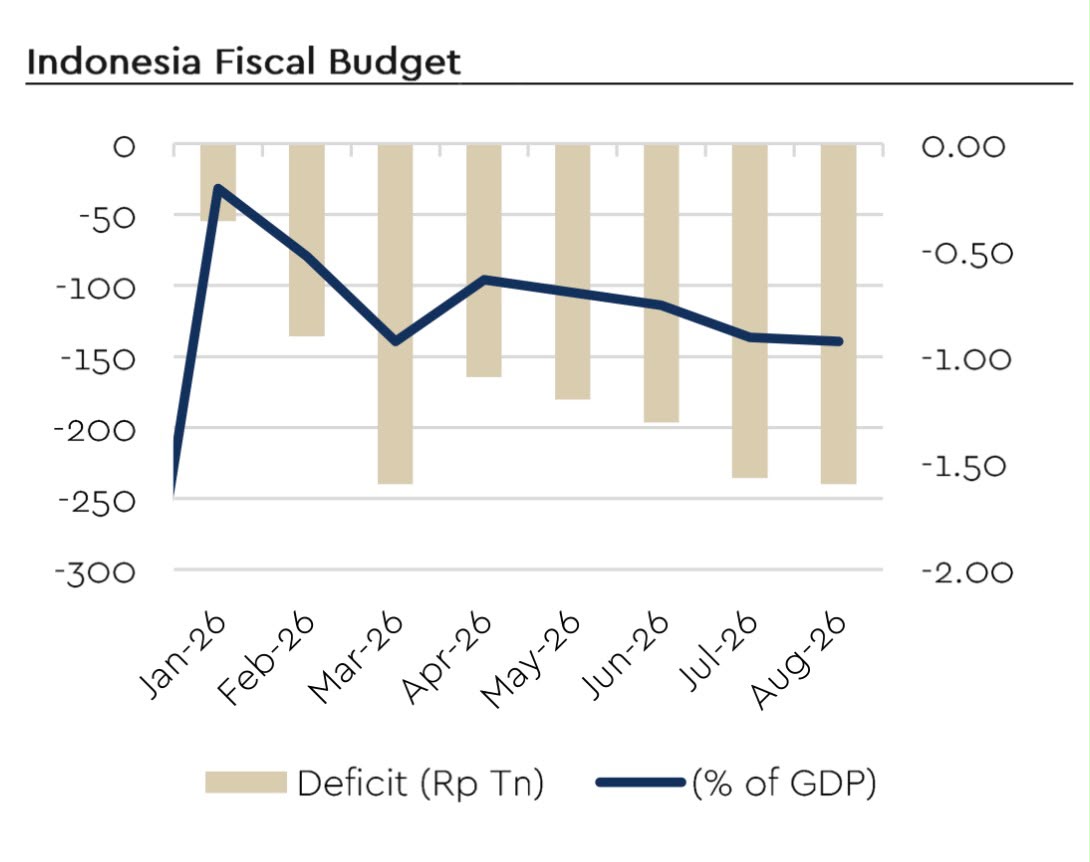
Beyond BI, a few other threads are in play. On the fiscal side, new Finance Minister Suahasil Nazara flatly denied any near-term plan to breach the 3% deficit ceiling, pinning 2026 at 2.85% of GDP. Deficit realization through August sits at just 0.93% of GDP (Rp240.1tn), with primary balance up 50.0% to Rp154tn from July's Rp102.7tn — a print that quietly resets the risk premium on Indonesian bonds. The revenue story has a twist, though: oil was the main driver, not tax collection. PPh Migas is growing significantly, non-tax revenue surged 41.7% to Rp435.1tn, and a Rp58tn BI surplus transfer padded the numbers further. This cuts both ways — Brent above US$100/bbl versus the government's US$75/bbl 2026 assumption helps for now, but Pertamina and PLN have already absorbed Rp331.4tn in energy compensation through August, and K/L spending is accelerating fast at +33% yoy. On SAL placement, Rp299tn is currently parked at Himbara with a Rp200tn floor committed through July 2027 — a positive signal for liquidity going forward.
Regionally, Vietnam officially upgraded from Frontier to FTSE Secondary Emerging Market status effective September 21, putting it on par with Indonesia for classification. FTSE estimates this could draw up to US$6bn in potential inflows, and anticipatory foreign buying was already visible on HOSE pre-reclassification, even as broader net selling continued there. For Indonesia, this is best read as a reallocation risk rather than a confirmed outflow — but it raises regional competition for foreign flows at a moment when Indonesia is still rebuilding credibility post-MSCI.
Two more domestic threads round out the picture: the DPR is scheduled to bring the Agrarian Reform bill to plenary, focused on land redistribution and reducing ownership inequality, with implementation concerns already weighing on property and plantation sector sentiment; and renewed chatter about revising the 3% deficit ceiling keeps fiscal credibility in focus, even as the government maintains its commitment to staying under that line. Sitting above all of this, the still-unresolved US-Iran tension remains the wildcard — a channel BI can't directly offset, capable of overriding the domestic rate story entirely if it escalates further.