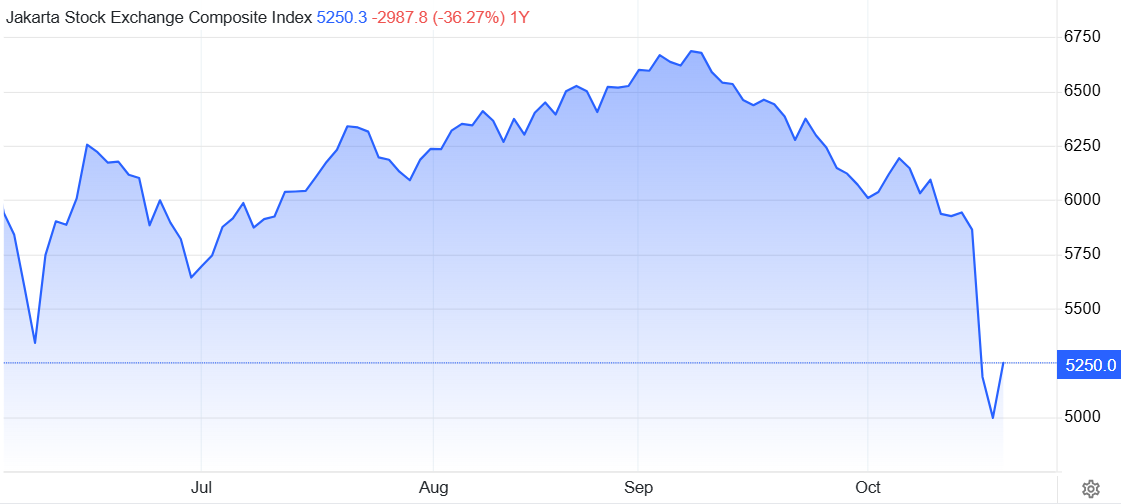
Indonesian equities have started to rebound today after another sell-off yesterday. The JCI has fallen more than 20% since MSCI opened a consultation on a potential two-notch downgrade of Indonesia to Standalone Market status. This is not yet a final decision: feedback remains open until April 30, 2027, and the final decision is expected on June 30, 2027, so regulators still have time to address MSCI’s concerns.
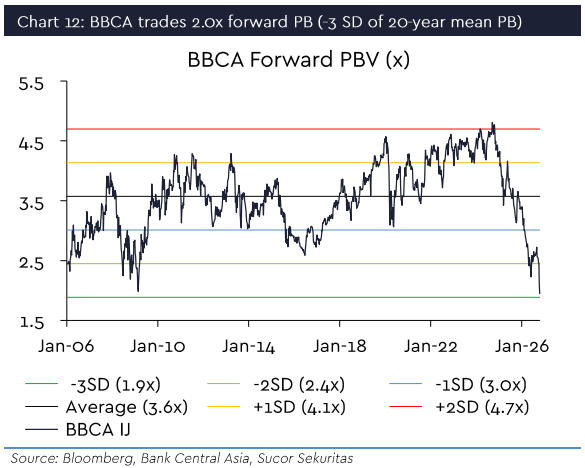
The sharp correction has made banking valuations far more compelling. BBCA trades at 2.2x P/B, a level rarely seen in recent years, while BBRI and BMRI trade at around 1.1x-1.2x P/B, potentially near their lowest levels since the COVID era. Selling pressure could persist while panic dominates sentiment, and a single day’s bounce does not necessarily mark a turning point. However, if regulatory measures successfully address MSCI’s concerns, a reversal could emerge quickly. We therefore advocate a staggered accumulation strategy: initiate a partial position, add exposure gradually on further weakness, and keep sufficient cash to navigate additional volatility.
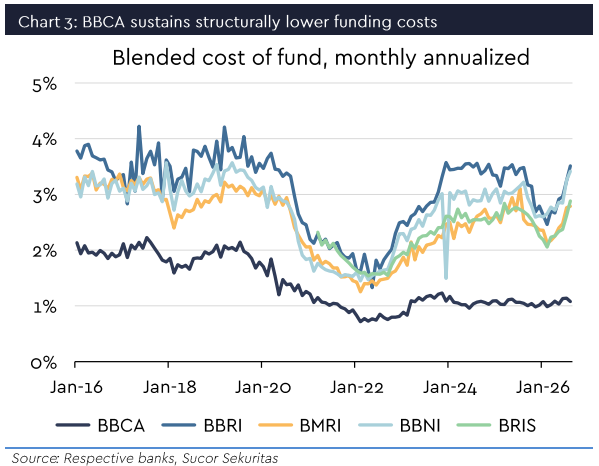
Among the major banks, BBCA remains the most compelling defensive exposure. Its profitability is industry-leading, and it comes from strong operating fundamentals rather than aggressive balance-sheet expansion or excessive leverage. Its key advantage is funding: a deeply entrenched transaction banking ecosystem keeps its deposit base stable and low-cost while peers face rising funding costs. Its ample liquidity lets BBCA keep lending without joining deposit rate wars, which protects its net interest margin and gives it flexibility when credit demand weakens. Improving cost efficiency and conservative loan-loss reserves provide an additional cushion against asset-quality deterioration, helping contain earnings volatility through this cycle.
Our forecasts already reflect a cautious stance, with loan growth moderating to around 5-6% and credit costs rising from historically low levels. BBCA’s funding advantage, cost discipline, and resilient fee income should offset part of these pressures, preserving its earnings capacity and positioning it for a stronger rebound as conditions improve. We reiterate our BUY rating with an unchanged target price of Rp6,800 (about 2.7x forward P/B). The stock trades at a discount to its historical valuation despite its largely intact structural advantages, making this an attractive opportunity to accumulate a high-quality franchise at a more reasonable price.
Outside banking, exporters have already outperformed, so investors should be more selective on entry points. Even so, US dollar earners remain attractive as a hedge against rupiah weakness, amid rising global risk aversion, elevated oil prices, and the risk of broader financial stress. Our top picks are AMMN, ADMR, AADI, MBMA, ANTM, and PGAS. On gold stocks, we are staying patient: the sector could become attractive again if gold prices correct below US$4,000/oz, offering a re-entry opportunity at more favorable valuations.