IHSG rebounded above 5,100 on Tuesday, closing 1.02% higher at 5,125.73, led by industrials, basic materials, and consumer discretionary stocks. The recovery follows the recent break below 5,000, with the index moving back above its 20-day moving average. While the rebound has improved short-term momentum, it remains too early to confirm a sustained recovery, particularly as foreign flows and broader market confidence remain key factors to watch.
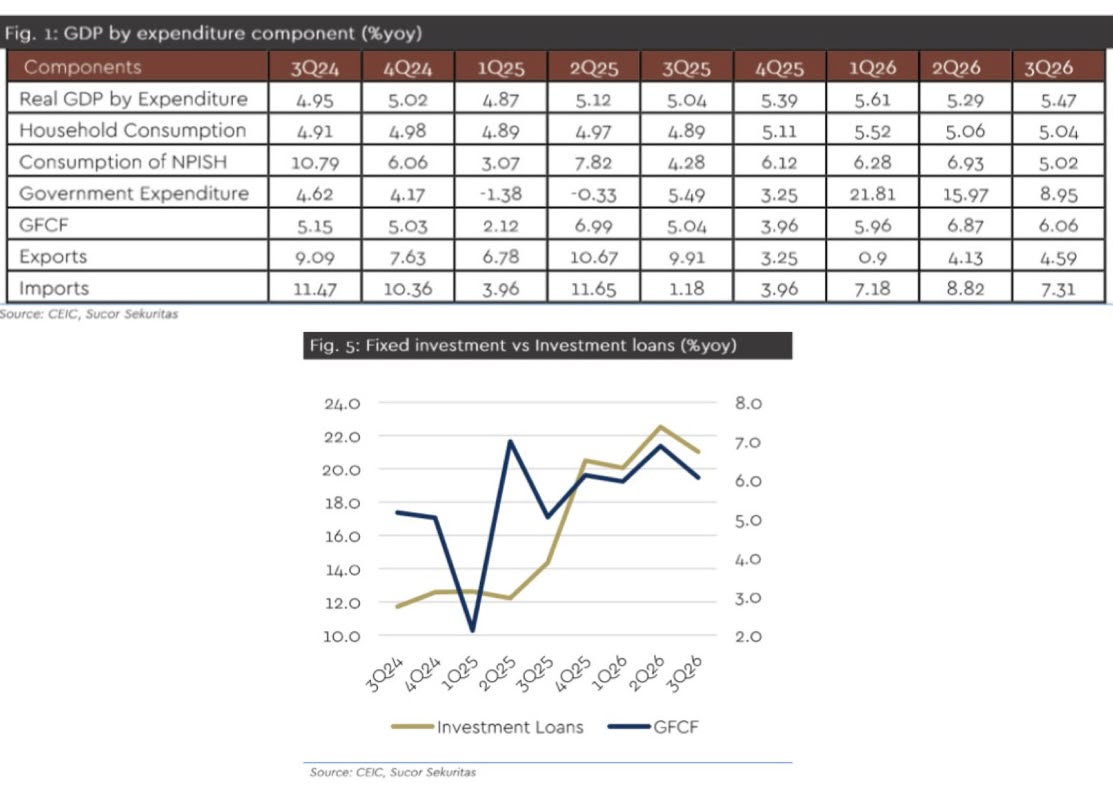
Indonesia’s economic growth remained resilient, with 3Q26 GDP expanding 5.47% YoY, supported by stronger investment and manufacturing activity. Gross fixed capital formation grew 6.06%, while manufacturing expanded 5.87%. Government consumption also contributed, rising 8.95% YoY, although household consumption remained relatively subdued. Meanwhile, consumer confidence improved in October, and lower oil prices could help ease the country’s energy import bill.
Higher auction yields remain a key caveat, as investors continue to demand higher returns despite sustained demand at the latest government bond auction. This keeps borrowing costs in focus, reinforcing our short-to-mid duration preference in bonds.
Looking ahead, the MSCI November Index Review announcement on 12 November (Jakarta time) could introduce volatility through potential index-related flows. Separately, US October CPI has been released, showing headline inflation rising 0.4% MoM and core inflation increasing 0.3% MoM. Our stance remains constructive but disciplined: we prefer to add exposure gradually rather than chase the rebound, while keeping cash available for potential volatility and focusing on banks and US dollar earners.