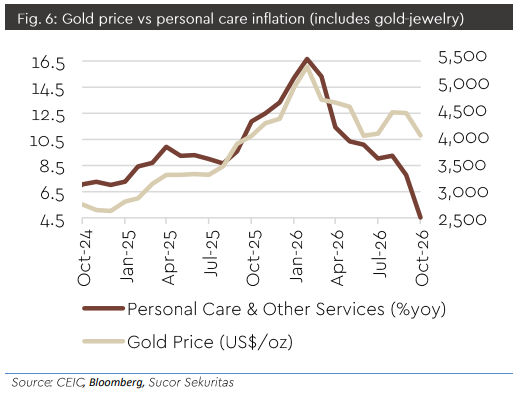
October inflation eased slightly, but the improvement is flattering. Headline inflation came in lower for the first time in four months, yet the drop in core was largely a high base effect from last year’s gold rally. Notably, core inflation stayed subdued despite a sharp rupiah depreciation, which suggests limited pass-through, likely reflecting weak consumer demand and producers who cannot easily raise prices. Rice supply and year-end demand are upside risks, but Bulog’s ample reserves should help contain retail prices. We expect inflation to stay in a similar range through year-end.
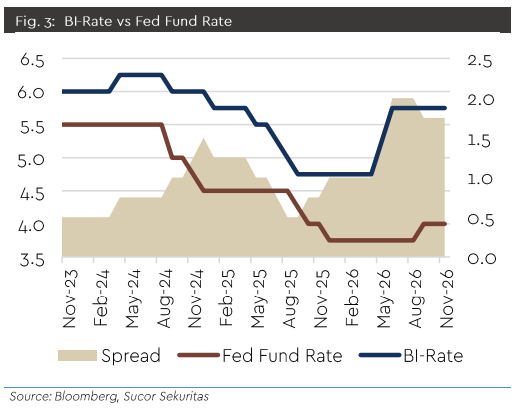
External pressure, not inflation, could drive a BI hike. With the real policy rate still positive, BI has no inflation case to tighten. The pressure comes from outside: the narrow rate gap versus the Fed and continued rupiah weakness, with the currency slipping further to start November. BI held at 5.75% last month, but we see a 25bp hike to 6.00% by December as our base case, with currency stability taking priority over growth.
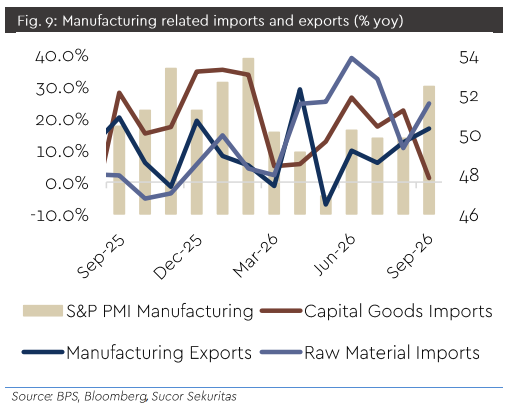
The trade surplus is still positive, but its quality is weakening. September’s surplus was roughly flat versus August and well below last year, and the year-to-date surplus has shrunk sharply. The non-oil sector carried the month, led by manufacturing and palm oil exports, while the oil and gas deficit remained a drag. On the import side, raw material purchases are rising, a sign production is still running, but capital goods imports are nearly flat, hinting at a moderating investment cycle. A surplus that leans more on commodity prices and Chinese demand offers limited support for the rupiah, so currency stability will depend more on portfolio flows than on trade.
Market shows resilience, but not yet recovery. The IHSG plunged at the open before recovering to close marginally higher, a sign of bargain-hunting rather than a confirmed turn in sentiment. We stay cautious and selective, favoring resilient earnings and strong balance sheets until the market stabilizes.
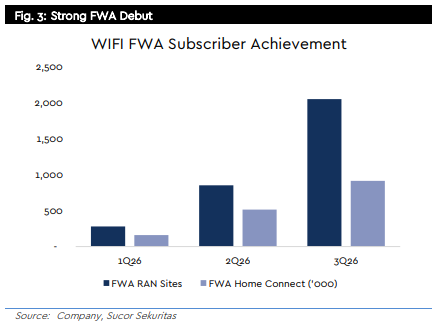
WIFI is one example of earnings holding up. Third-quarter profit surged, with earnings quality improving on strong operating cash flow and cash conversion. FTTH and FWA expansion is accelerating, and a healthy cash position gives it room to keep investing. We reiterate BUY with a lower TP of Rp5,000, reflecting a higher discount rate, though the aggressive investment cycle and negative free cash flow warrant monitoring.