Global bond markets are under significant pressure, with sovereign yields across the US, UK, Europe, and Japan reaching multi-decade highs. While the sell-off has not yet triggered a systemic crisis, rising yields are tightening financial conditions, increasing borrowing costs, and heightening market volatility. The pressure reflects persistent inflation, higher energy prices, growing government debt issuance, reduced central-bank bond purchases, and increasing competition for capital from AI-related financing. Although credit spreads remain relatively contained, sustained US 10-year Treasury yields above 5.25–5.50% could increase refinancing costs and corporate default risks.
For global equities, higher yields are pressuring valuations, particularly for growth stocks, with weaker earnings potentially following if financing conditions remain tight. In Indonesia, US Treasury yields above 5.5% could accelerate foreign outflows, weaken the rupiah, and limit Bank Indonesia’s room to ease monetary policy. Banks and property remain vulnerable, while coal, nickel, and other energy exporters may prove more resilient if commodity prices stay firm, although higher energy costs could add to fiscal pressure.
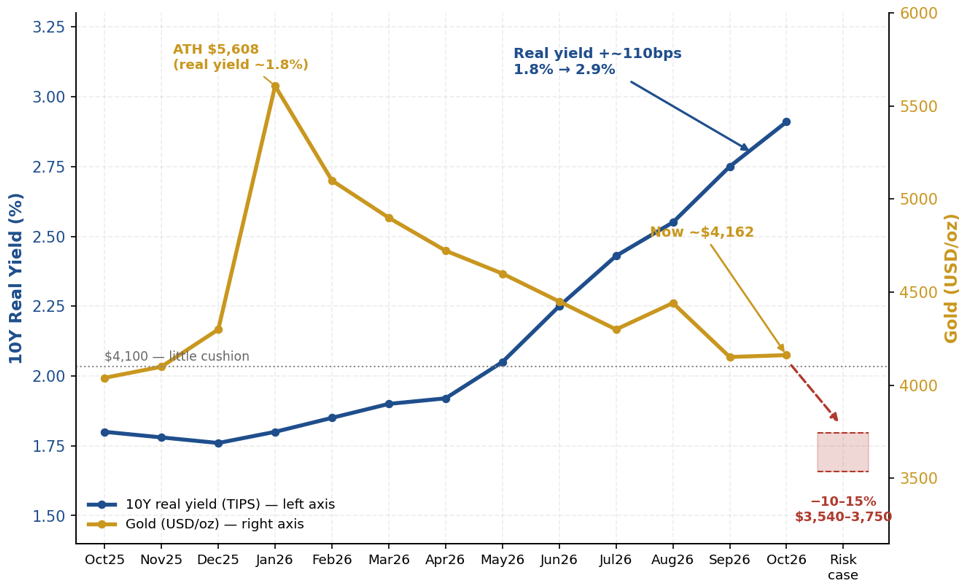
Gold remains exposed to further downside as real yields rise. Higher real yields increase the opportunity cost of holding gold, which generates no interest income, while a stronger US dollar and ETF outflows could add to selling pressure. With the Fed still potentially raising rates if inflation remains persistent, real yields could climb further, weighing on gold prices. Although central-bank purchases may provide support, they may not fully offset weaker investment demand.
We would avoid chasing gold at current levels and wait for a more attractive entry point. Once inflation cools and the Fed signals a pause in rate hikes, particularly if real yields begin declining, gold could offer a better risk-reward opportunity. Our base case is a 10–15% pullback rather than a structural collapse, creating room for gradual accumulation in tranches at lower levels while maintaining sufficient liquidity.