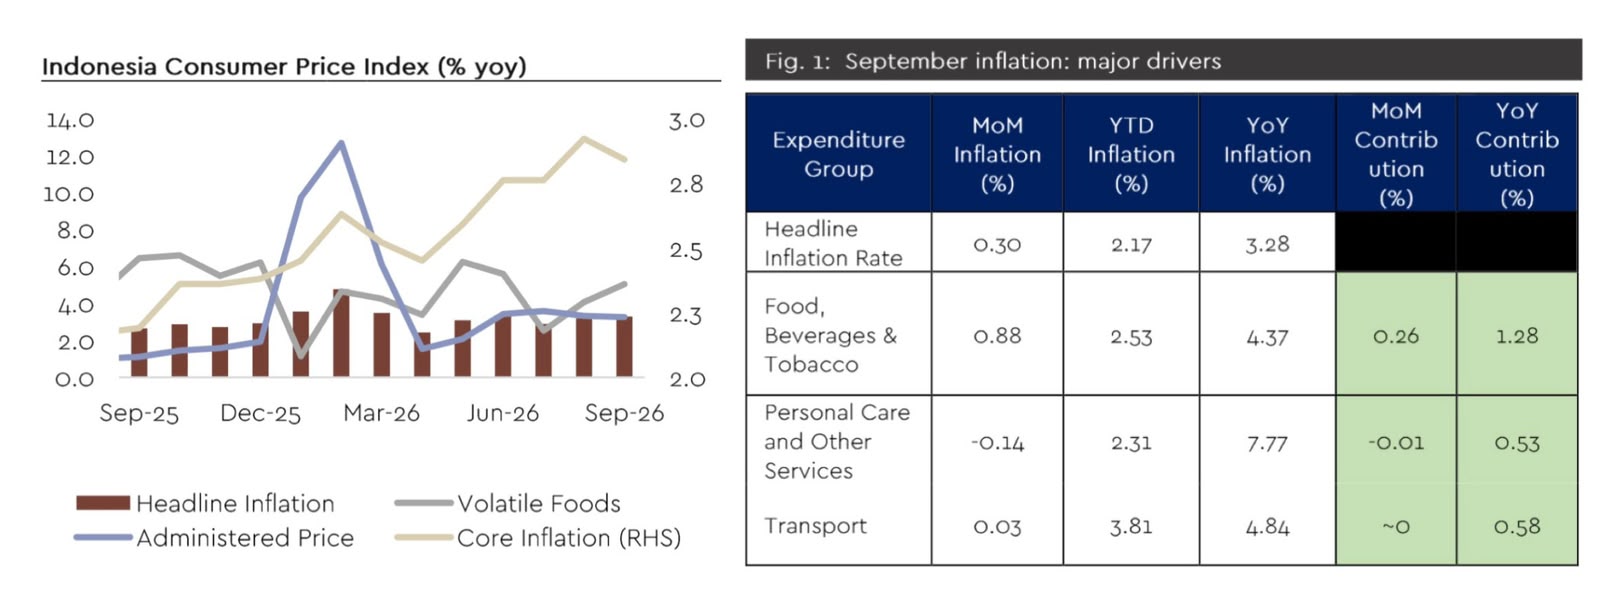
Inflation is rising, but not driven by stronger domestic demand. Headline CPI climbed to 3.28% yoy in September from 3.19% in August, marking the third consecutive month of higher annual inflation. However, the increase was mainly driven by volatile food prices, while core inflation continued to ease, suggesting that underlying demand-side pressure remains soft. Excluding gold, which contributed significantly to headline inflation, we estimate core inflation at around ~2.2% yoy. We project October inflation at 3.10% yoy, with supply-side pressures remaining the main concern.
The latest trade data also points to a weaker external backdrop. Indonesia’s August trade surplus widened to US$3.55bn, the largest since September 2025, but the improvement was largely driven by a sharp decline in imports rather than stronger exports. Export growth remained modest, while the oil and gas deficit continues to widen. We expect the September trade surplus to narrow to around US$1.86bn, with the current account deficit improving in 3Q26 but remaining elevated into 2027.
This weaker export momentum means the rupiah is becoming increasingly reliant on foreign capital flows. With US 10-year yields at their highest level since 2007, foreign holdings of SBN have declined significantly, while the rupiah has recently touched Rp18,000/US$. Higher global oil prices add another layer of imported inflation risk. We therefore expect BI to remain focused on rupiah stability and potentially deliver another rate hike in 4Q26, even as domestic demand remains relatively soft.
Against this macro environment, AMMN stands out on improving company-specific fundamentals. 2Q26 net profit reached US$338mn, up 111% qoq, reversing the loss recorded in 2Q25 and bringing 1H26 earnings to US$498mn. The improvement was driven by the return of concentrate sales, with copper and gold concentrate revenue together accounting for 66% of quarterly revenue.
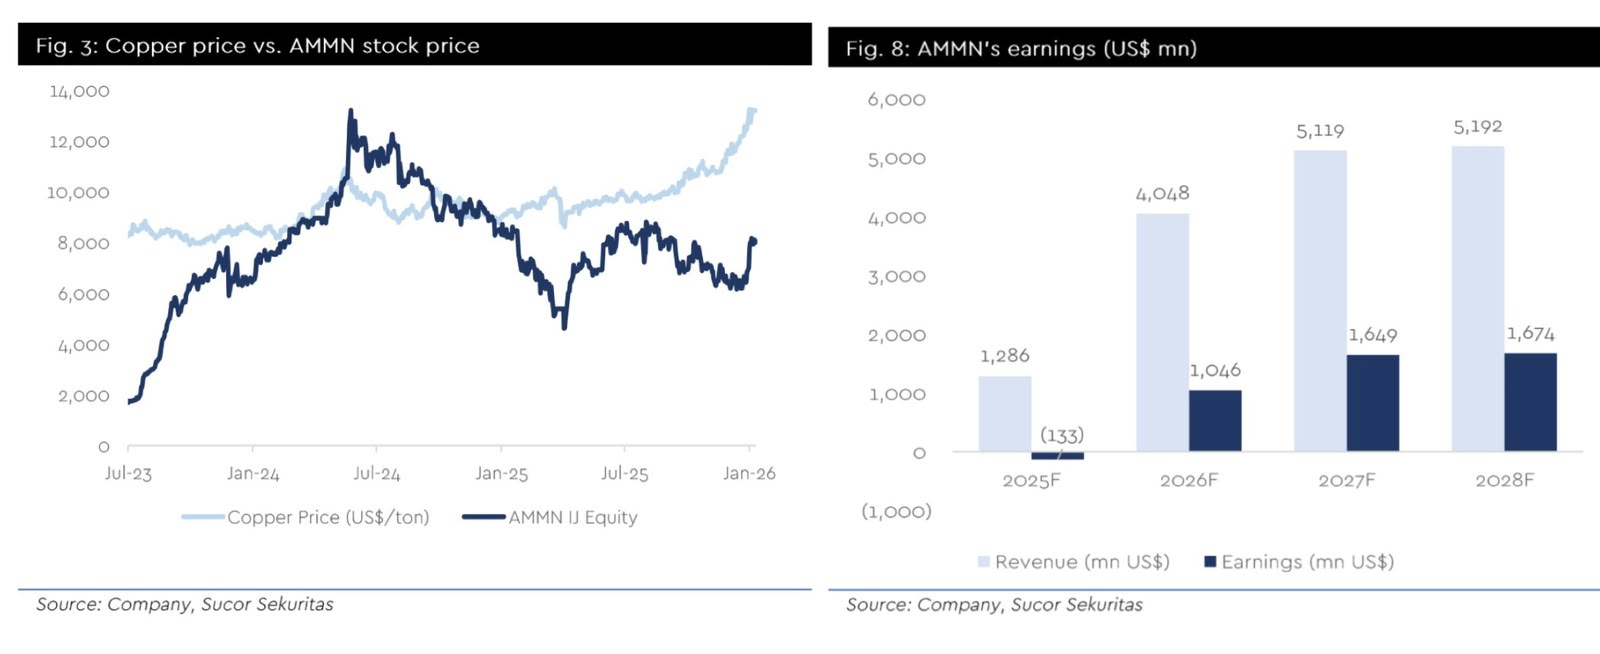
Looking ahead, we lower our 2026F net profit forecast by 10%, but raise our 2027F earnings forecast by 9%, supported by stronger copper prices and higher production that should improve operating leverage. We maintain our BUY view, with Batu Hijau remaining the largest contributor to our valuation.