15 September 2026
Stability Over Disruption
Market Commentary
0 comments
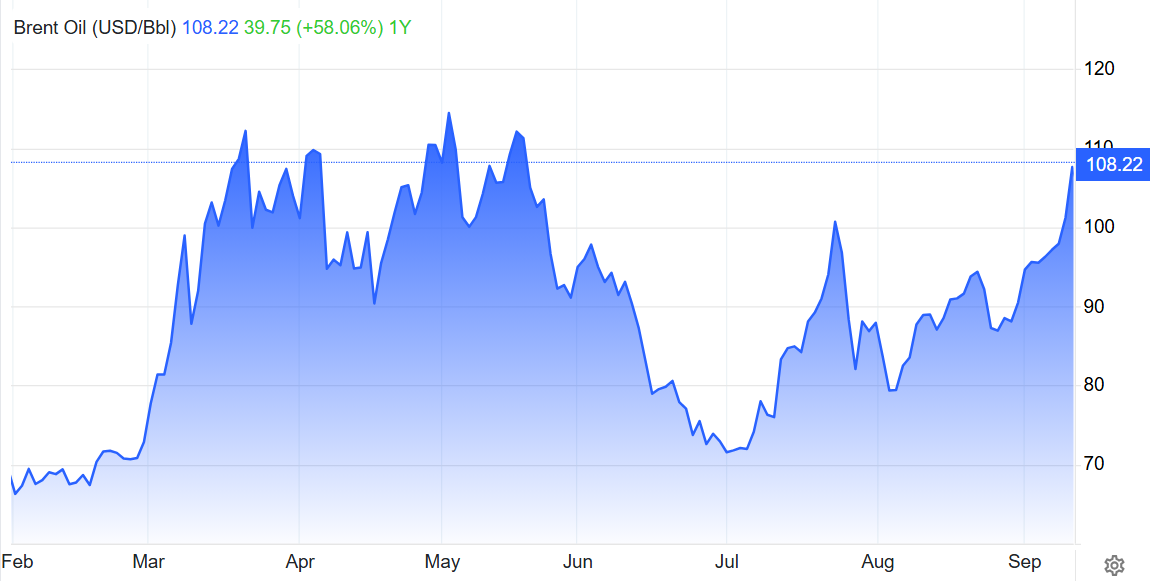
Brent crude rose ~2% to US$108.22/bbl, on US–Iran tensions, keeping inflation risks elevated and increasing the odds of a more hawkish Fed. Domestically, the JCI rebounded to close nearly flat at -0.10% after falling more than 2% intraday on Monday, with sentiment improving following the appointment of Suahasil Nazara as the new Finance Minister, replacing Purbaya Yudhi Sadewa.
We read Nazara's appointment as a continuity pick rather than a disruption one. A career technocrat with experience as Deputy Finance Minister since 2019 and former head of BKF, Nazara brings strong institutional memory across fiscal policy and monetary coordination. His commitment to keeping the fiscal deficit below 3% of GDP should provide comfort that Indonesia will maintain a prudent fiscal path while continuing priority government programs. In the current environment, we see this as a stability-first approach, prioritizing fiscal credibility over aggressive policy changes.
Separately, we are watching a potential structural shift in global capital allocation, with capital, reserves and gold increasingly flowing back toward Europe, China, Japan and other home markets. The US Senate's CLARITY Act vote on September 15 could further accelerate stablecoin adoption and demand for short-dated US Treasuries. Over the longer term, easier access to tokenized global assets could also encourage Indonesian investors to diversify beyond domestic equities, potentially creating a new dynamic for local market flows.
We still favor selective exposure to AMMN, MBMA and ISAT. AMMN offers exposure to the structural copper demand from AI and power-grid investment, while MBMA benefits from Indonesia's expanding nickel ecosystem and downstream capacity. ISAT provides a different angle through AI infrastructure, with Zankore's planned 200MW AI capacity potentially becoming a meaningful contributor to group revenue and EBITDA over the coming years.
We read Nazara's appointment as a continuity pick rather than a disruption one. A career technocrat with experience as Deputy Finance Minister since 2019 and former head of BKF, Nazara brings strong institutional memory across fiscal policy and monetary coordination. His commitment to keeping the fiscal deficit below 3% of GDP should provide comfort that Indonesia will maintain a prudent fiscal path while continuing priority government programs. In the current environment, we see this as a stability-first approach, prioritizing fiscal credibility over aggressive policy changes.
Separately, we are watching a potential structural shift in global capital allocation, with capital, reserves and gold increasingly flowing back toward Europe, China, Japan and other home markets. The US Senate's CLARITY Act vote on September 15 could further accelerate stablecoin adoption and demand for short-dated US Treasuries. Over the longer term, easier access to tokenized global assets could also encourage Indonesian investors to diversify beyond domestic equities, potentially creating a new dynamic for local market flows.
We still favor selective exposure to AMMN, MBMA and ISAT. AMMN offers exposure to the structural copper demand from AI and power-grid investment, while MBMA benefits from Indonesia's expanding nickel ecosystem and downstream capacity. ISAT provides a different angle through AI infrastructure, with Zankore's planned 200MW AI capacity potentially becoming a meaningful contributor to group revenue and EBITDA over the coming years.
Written by Boris, the Broker
Comments